

Current Used Vehicle Market Conditions and Outlook
Average auction prices in June were up from year-ago levels for the fourth month in a row, but were lower than in May. According to ADESA Analytical Services’ monthly analysis of Wholesale Used Vehicle Prices by Vehicle Model Class, average auction prices in June were up 1.2 percent from year-ago levels, but down 1.5 percent relative to the previous month.
Average auction prices in June were up from year-ago levels for the fourth month in a row, but were lower than in May. According to ADESA Analytical Services’ monthly analysis of Wholesale Used Vehicle Prices by Vehicle Model Class, average auction prices in June were up 1.2 percent from year-ago levels, but down 1.5 percent relative to the previous month. Car prices generally registered solid gains, with full-size, compact, and sporty cars making the strongest year-over-year price gains. Truck prices – especially for full-size SUVs – showed declines, possibly reflecting high gas prices. Generally more fuel-efficient Mini SUVs were the only truck segment to register double-digit year-over-year price increases, which reinforces this hypothesis.
Retail demand has been one key driver of the overall firming trend in wholesale prices during the last twelve months. ADESA Analytical Services cited May 2003 as an “inflection point” in the market based on our observation at the time that retail used vehicle prices as a percent of new vehicle prices were at historical lows (below 50 percent at franchised dealerships). These relatively low retail prices, along with a recovering economy and other factors, helped stimulate retail used vehicle sales.
Although retail used vehicle sales continue to be brisk, the rate of increase versus year-ago levels has been tapering as we enter the months corresponding to the period after last year’s inflection point. According to data from CNW Marketing/Research, year-over-year retail sales growth has declined from 10.5 percent in April, to 10 percent in May, to 9.3 percent in June. For independent dealers these percentages have gone from 20.1 percent to 16.1 percent to 14.1 percent. It is important to note, however, that on a year-to-date basis through June, independent dealers have sold more vehicles than at any time since CNW has been compiling this data. This is especially encouraging considering that last year through June, independent dealers were suffering through what might have been their worst first-half ever.
The other major driver in the firming price environment is declining supply – primarily from off-lease vehicles. A reflection of this is that the ADESA Auction Inventory Index now stands at 88.3 – 27 percent below its year-ago level, and 17 percent below May month-end. This result was anticipated in ADESA Analytical Services’ 2003 Global Vehicle Remarketing report, where we projected nearly a 230,000-unit drop in off-lease volume between 2003 and 2004.
Auction industry conversion rates (vehicle sold as a percent of vehicles offered) appear to be settling at their historical norm of roughly 40 percent for dealer-to-dealer units and 60 percent for all units processed. A reflection of this is that the ADESA Auction Dealer Optimism Index was down modestly in June after being up for thirteen months in a row. This means that dealers purchased a lower percentage of vehicles offered for sale by other dealers at ADESA auctions than they did last year – another indication that retail demand is tapering to more traditional summer levels after a strong spring.
More Operations
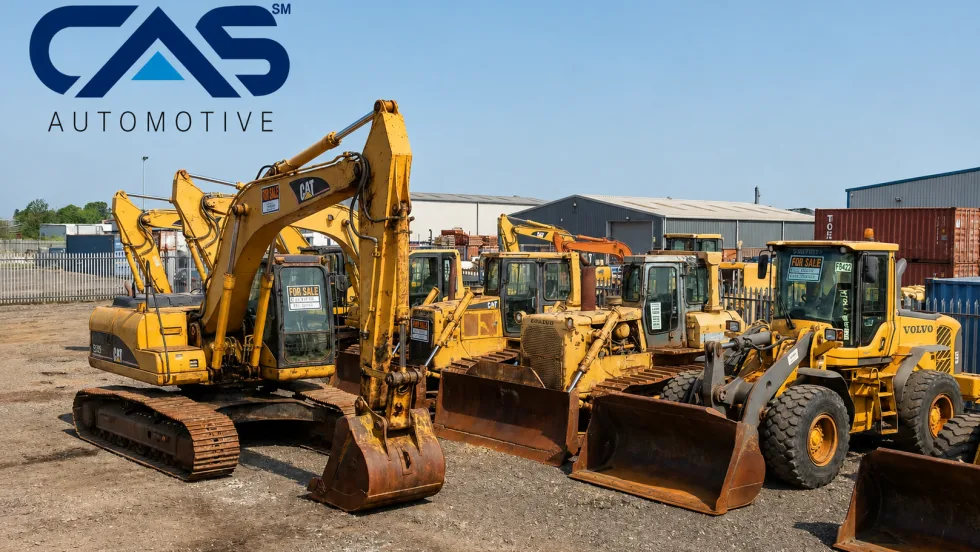
CAS Automotive Launches Remarketing Service for Damaged, Surplus Equipment
Damaged Equipment expands CAS Automotive’s vehicle remarketing model to commercial equipment, targeting fleet operators, insurers, equipment dealers, and rental companies.
Read More →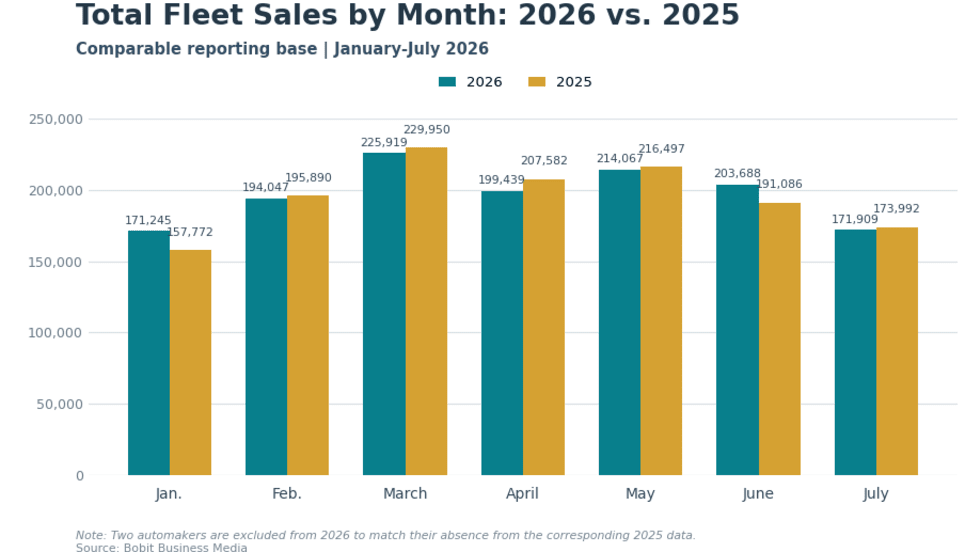
Fleet Sales Hold Steady as Commercial Gains Offset Rental Decline
Commercial and government fleet sales increased through July 2026, offsetting most of the decline in rental volume and leaving combined comparable fleet sales 0.5% above the same period last year.
Read More →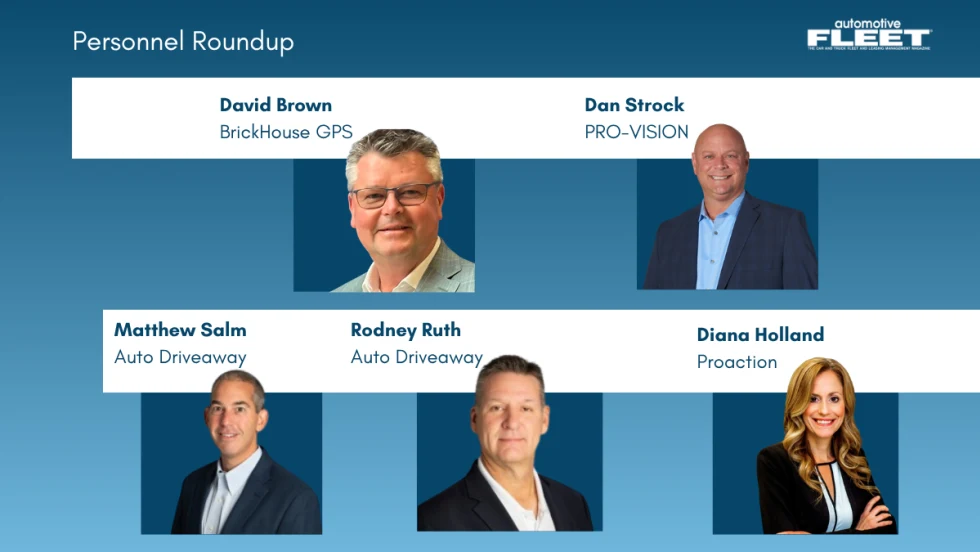
Personnel Update: BrickHouse GPS, PRO-VISION, Auto Driveaway, and Proaction
Check out the latest must-know fleet personnel updates from the last couple of months.
Read More →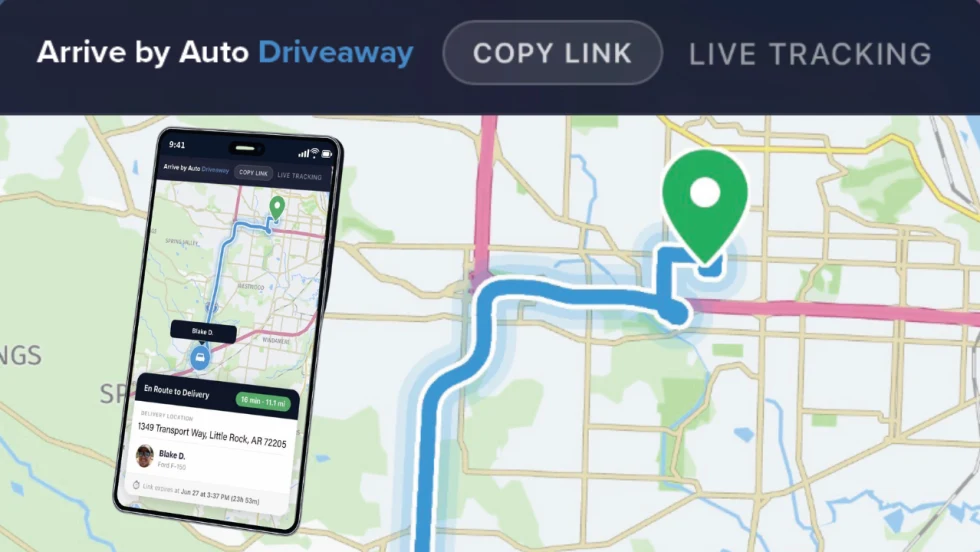
What Comes Next for Auto Driveaway?
A new Auto Driveaway feature called Arrive provides recipients with live location updates and ETAs during the final hour of a vehicle move, while fleet customers continue to have end-to-end shipment visibility through the company's customer portal.
Read More →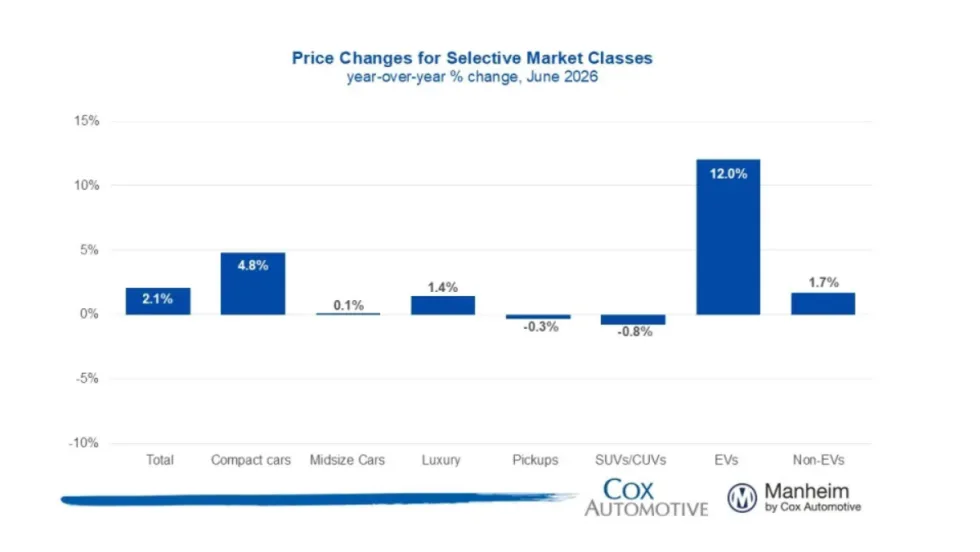
Manheim Index Shows Used-Vehicle Wholesale Prices Up 2.1% in June
The market is seeing stronger appreciation in older used vehicles this year, and the most affordable segments have been among the year’s best performers.
Read More →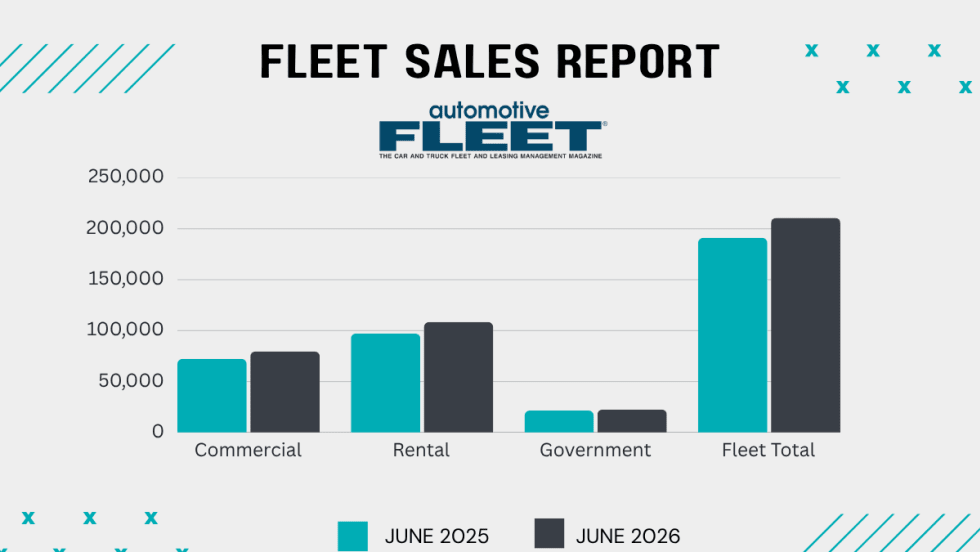
Commercial Fleet Sales Contribute To June, YTD Gains
The fleet sector has boosted its vehicle purchases at a reliable pace in the first half of this year compared with 1H 2025.
Read More →
Stop Remarketing Electric Vehicles Like Gas Cars
The advantages and attributes of electric vehicles are upending the traditional remarketing cycle, requiring fleet sellers to rely on new factors and approaches detailed below.
Read More →
AP Fleet Management Expands Remarketing Program for Commercial Work Trucks
AP Fleet Management expanded its commercial vehicle remarketing program with dedicated resale services and an online marketplace for used work trucks.
Read More →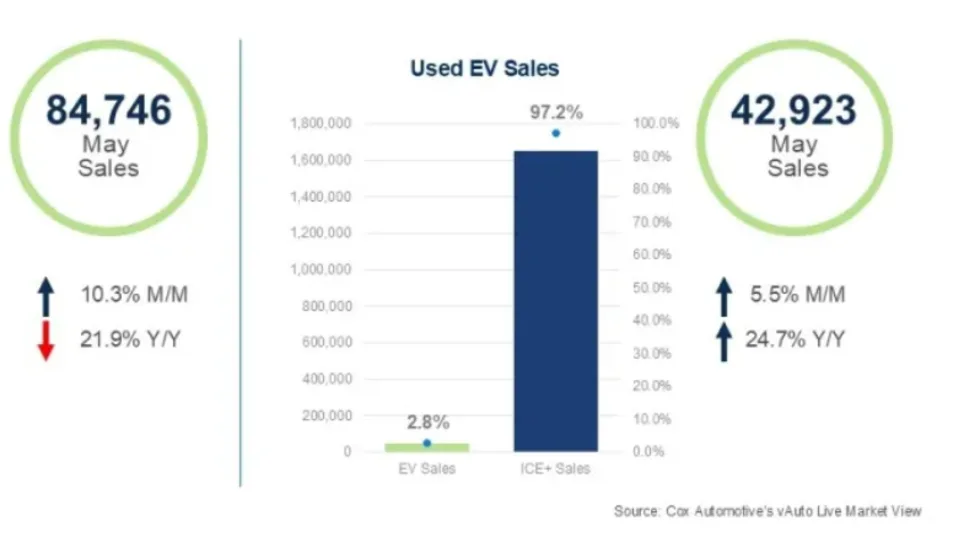
Used EVs Strengthen Overall Electric Vehicle Market
The latest sales data point to several reasons for the divergent trends in new and used EVs that can factor into fleet cycling decisions.
Read More →
The Data-Driven Haul: 5 Ways AI is Leveling the Playing Field in Auto Transport
Large and small transport fleets are becoming more competitive as predictive analytics and real-time data inform the logistics decision chain.
Read More →