Edmunds.com Reports True Cost of Incentives; Chrysler Remains Highest Spender
Edmunds.com, an online resource for automotive information, reported that the average manufacturer incentive per vehicle sold in the United States was $2,459 in February 2004, up $324, or 15.2 percent, from February 2003, and up $94, or 4 percent, from January 2004.
Edmunds.com, an online resource for automotive information, reported that the average manufacturer incentive per vehicle sold in the United States was $2,459 in February 2004, up $324, or 15.2 percent, from February 2003, and up $94, or 4 percent, from January 2004.
Edmunds.com's monthly True Cost of IncentivesSM (TCISM) report takes into account all of the manufacturers' various United States incentives programs, including subvented interest rates and lease programs as well as cash rebates to consumers and dealers. To ensure the greatest possible accuracy, Edmunds.com bases its calculations on sales volume, including the mix of vehicle makes and models for each month, as well as on the proportion of vehicles for which each type of incentive was used.
Overall, combined incentives spending for domestic Chrysler, Ford, and General Motors nameplates increased by 1.7 percent to $3,409 per vehicle in February, compared to $3,354 in January. Chrysler spent the most per vehicle for the second month in a row, reaching $3,857 per vehicle, up $6 over the previous month, while gaining 0.45 percent of market share. General Motors' incentives spending decreased by $29 to $3,450 per vehicle while its market share gained back a portion of the substantial loss incurred in January, climbing by 1 percent to 27.1 percent. After declining for four consecutive months, Ford's incentives spending increased by $202 to $3,031 per vehicle in February while its market share increased 0.3 percent to 19 percent.
In February Korean automakers spent $1,686, European automakers spent $1,596 and Japanese automakers spent $881 per vehicle sold.
Examining the data by brand, Edmunds.com found that Mini spent virtually nothing on incentives while Scion spent only $66 and Lexus spent only $159 per vehicle. At the other end of the spectrum, Oldsmobile continued to spend the most incentives dollars per vehicle at $5,191, followed by Lincoln at $4,540 and Mercury at $4,314.
Among vehicle segments, large cars had the highest average incentives last month at $3,881, followed by large SUVs at $3,224 and minivans at $3,220. Luxury SUVs had the lowest average incentives at $1,227, followed by luxury sports cars at $1,855 and sport cars at $1,884. Large SUVs gained the most market share since February 2003, increasing from 3.8 percent to 5.3 percent, while midsize cars lost the most market share during that period, down from 18 percent to 16.7 percent.
Industry average days-to-turn, which measures how many days on average it takes to sell vehicles after they arrive at dealerships, was 69 days in February compared to 64 in both January 2004 and February 2003. Isuzu had the longest days-to-turn at 144, followed by Mitsubishi at 121. The quickest inventory turnaround was for Scion at 13 days, followed by Mini at 23 days.
From January 2004 to February 2004 the Edmunds.com New Vehicle Price Index decreased 1 percent to 99.7 (base=100 set in January 2002). From February 2003 to February 2004, the Edmunds.com New Vehicle Price Index has increased by 2 percent from 97.7 to 99.7. Only a couple of the segments posted gains in February: vans saw the largest increase at 1.9 percent, followed by large SUVs at 1 percent. Compact cars had the most significant decline at 2.3 percent, followed by compact SUVs at 1.7 percent.
In February 2004, the sales-weighted average new vehicle sticker price was $29,153, 1 percent lower than in January 2004 but 3.9 percent higher than in February 2003. The sales-weighted average net price was $24,747 – 15 percent below MSRP and the highest since September 2003, when the discount from average MSRP to net price was 16 percent.
The average net price was 19.3 percent below MSRP for domestic automakers in February, compared to 18.5 percent in February 2003. Korean manufacturers' average net price was 14.4 percent below MSRP in February 2004, up from 10.5 percent the previous year. Japanese manufacturers' average net price was 9 percent below MSRP in February 2004, unchanged from last year. European manufacturers' average net price was 6.2 percent below MSRP in February 2004, up slightly from 6 percent last year.
More Operations
FLD Promotes Three Executives in Leadership Changes
FLD has promoted three longtime executives, naming Gary Mott CEO, Richard Mallek president, and Ron Sanders managing partner.
Read More →
CAS Automotive Launches Remarketing Service for Damaged, Surplus Equipment
Damaged Equipment expands CAS Automotive’s vehicle remarketing model to commercial equipment, targeting fleet operators, insurers, equipment dealers, and rental companies.
Read More →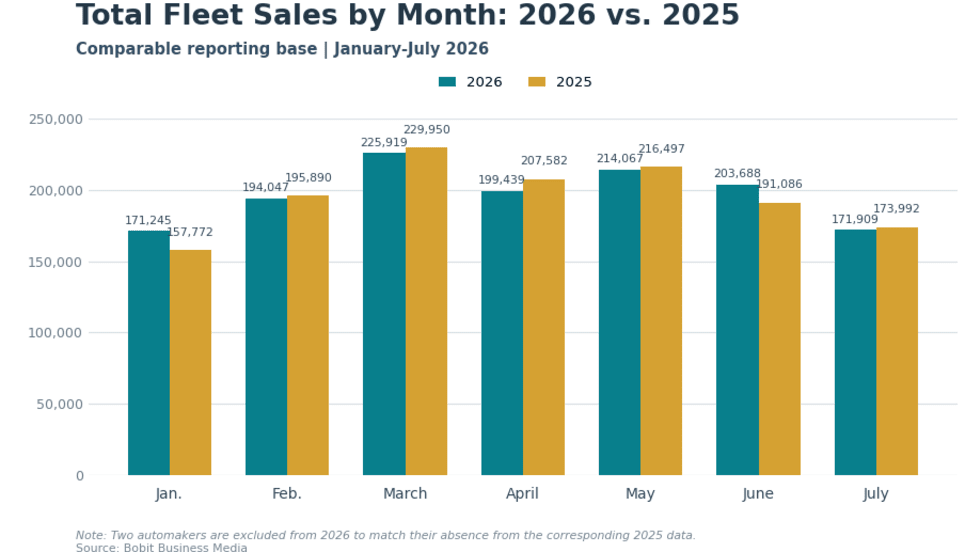
Fleet Sales Hold Steady as Commercial Gains Offset Rental Decline
Commercial and government fleet sales increased through July 2026, offsetting most of the decline in rental volume and leaving combined comparable fleet sales 0.5% above the same period last year.
Read More →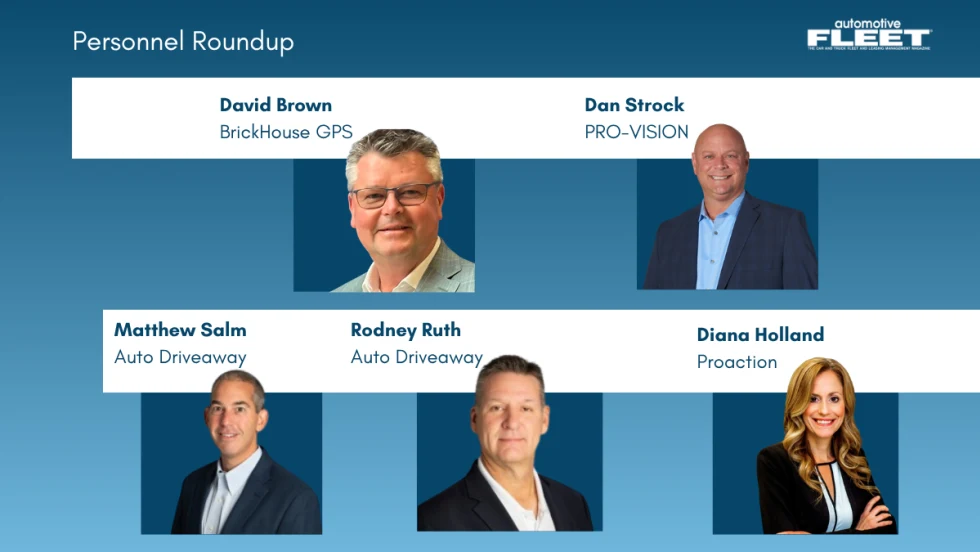
Personnel Update: BrickHouse GPS, PRO-VISION, Auto Driveaway, and Proaction
Check out the latest must-know fleet personnel updates from the last couple of months.
Read More →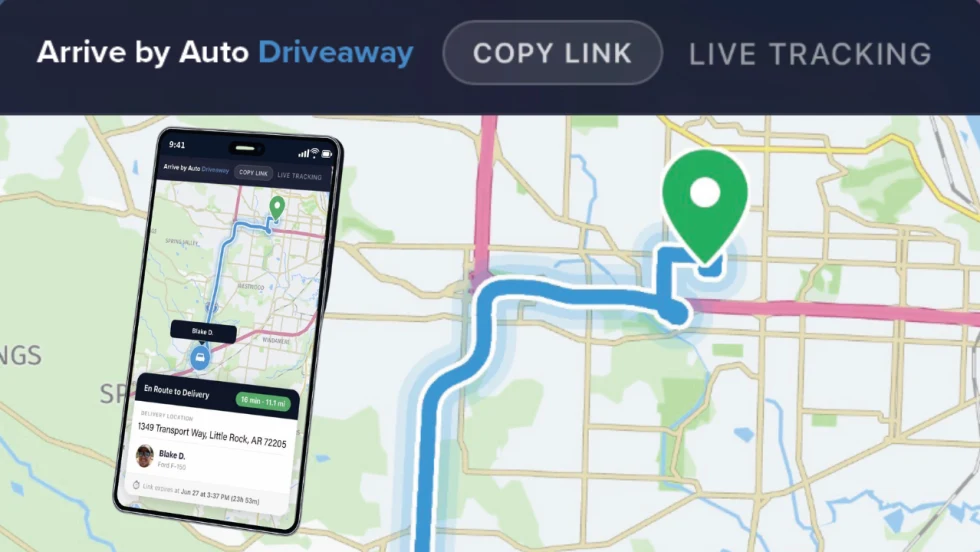
What Comes Next for Auto Driveaway?
A new Auto Driveaway feature called Arrive provides recipients with live location updates and ETAs during the final hour of a vehicle move, while fleet customers continue to have end-to-end shipment visibility through the company's customer portal.
Read More →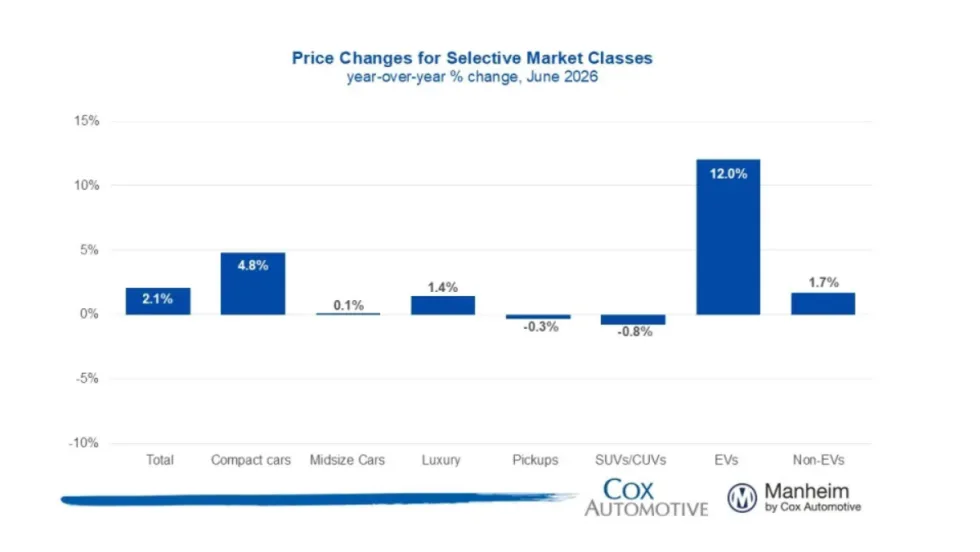
Manheim Index Shows Used-Vehicle Wholesale Prices Up 2.1% in June
The market is seeing stronger appreciation in older used vehicles this year, and the most affordable segments have been among the year’s best performers.
Read More →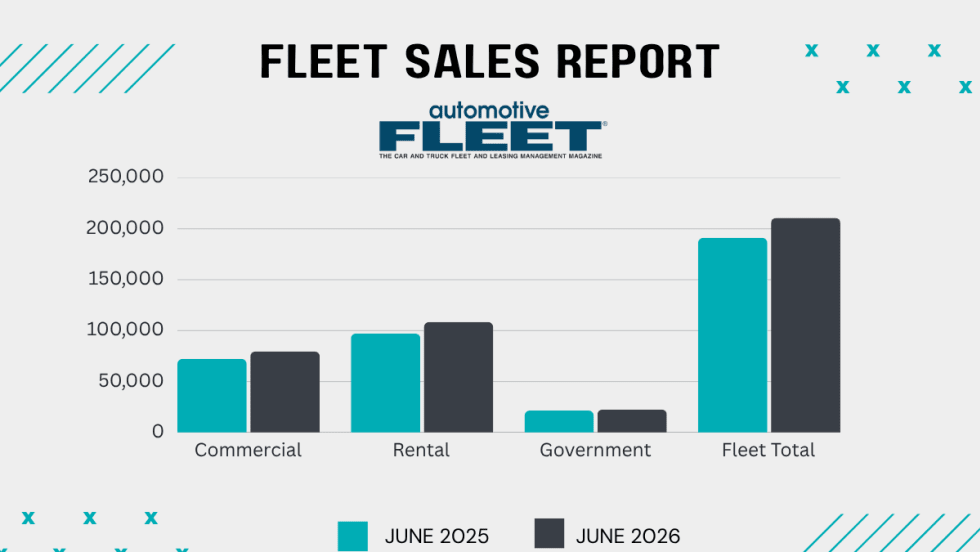
Commercial Fleet Sales Contribute To June, YTD Gains
The fleet sector has boosted its vehicle purchases at a reliable pace in the first half of this year compared with 1H 2025.
Read More →
Stop Remarketing Electric Vehicles Like Gas Cars
The advantages and attributes of electric vehicles are upending the traditional remarketing cycle, requiring fleet sellers to rely on new factors and approaches detailed below.
Read More →
AP Fleet Management Expands Remarketing Program for Commercial Work Trucks
AP Fleet Management expanded its commercial vehicle remarketing program with dedicated resale services and an online marketplace for used work trucks.
Read More →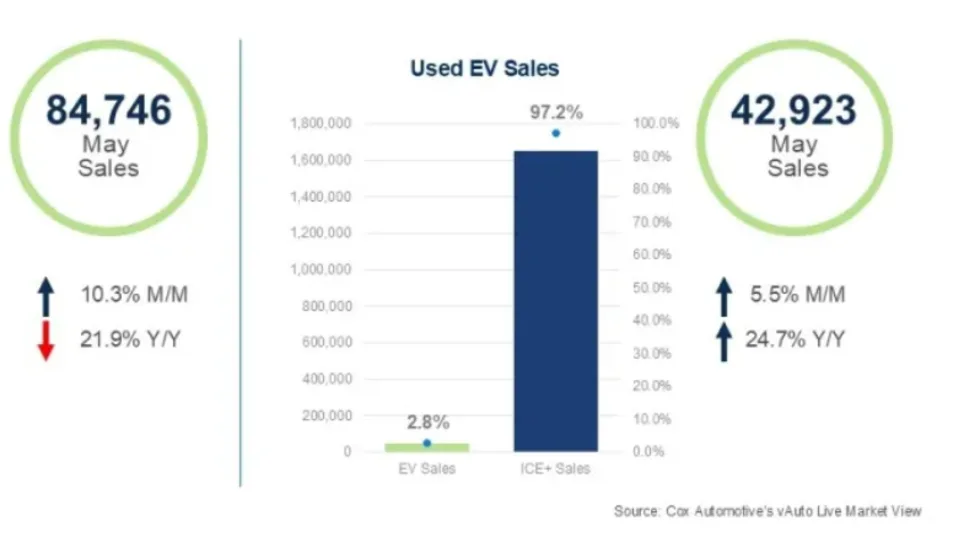
Used EVs Strengthen Overall Electric Vehicle Market
The latest sales data point to several reasons for the divergent trends in new and used EVs that can factor into fleet cycling decisions.
Read More →